Compiled by the YMTD Accounting Partner team · Information as of 7 November 2026
For retail, souvenir, and handicraft businesses, learning the regulations and how to get approved as a VAT refund store (VAT Refund for Tourists: VRT) is a crucial tax step to legally capture foreign tourist spending. The VAT refund program for tourists enables registered businesses to issue claim forms so international tourists can claim a VAT refund at international airports before departing the Kingdom [1]. However, in practice, many business owners still confuse "VAT refund for tourists (VRT)" with "export sales subject to 0% VAT," or mistakenly believe that stores can deduct the VAT stated on refund claim forms from their monthly output VAT. This article details the qualification criteria, application procedures, accounting obligations, and concrete P.P.30 (monthly VAT return) filing rules according to the Revenue Department [1][2][4].
Key Takeaways
- Juristic Person Qualifications and Registered Capital: Applicants must be a limited company (Co., Ltd.), public company, or registered partnership registered for VAT (holding a valid P.P.20 certificate). Paid-up registered capital must be at least 2,000,000 baht for establishments in Bangkok, or at least 500,000 baht for provincial regions (including Chiang Mai) [1].
- Application Submission and Review Period: Applications are submitted via Form Kor.Thor.1 (and Kor.Thor.1.1 for branches) at the local Area Revenue Office with no application fee. The Revenue Department takes approximately 30 working days to review documents and inspect the business premises pursuant to public service guidelines [1].
- Criteria for Issuing Form P.P.10: Foreign tourists must purchase goods totaling at least 2,000 baht (including 7% VAT) from the same merchant on the same day, present their original passport, and the store must always record the passport number on the full tax invoice [1].
- Filing P.P.30 Duties: Sales under the VRT scheme are treated as domestic sales subject to standard 7% VAT in full. The store must record output VAT and submit the monthly P.P.30 return by the 15th of the following month. The VAT amount stated on Form P.P.10 must never be deducted from the store's output VAT, as the Revenue Department refunds the tourist directly [2][4].
- Registry Reporting Duties (Form Kor.Thor.9): Once Form P.P.10 is issued, the store must prepare the "Report on the Issuance of VAT Refund for Tourists Applications (Form Kor.Thor.9)" within 3 days from the date of issuing Form P.P.10, and retain this report along with supporting evidence at the premises for at least 2 years [2].
Introduction & Scope: What Is a VAT Refund and Why Stores Must Understand the Tax System Correctly
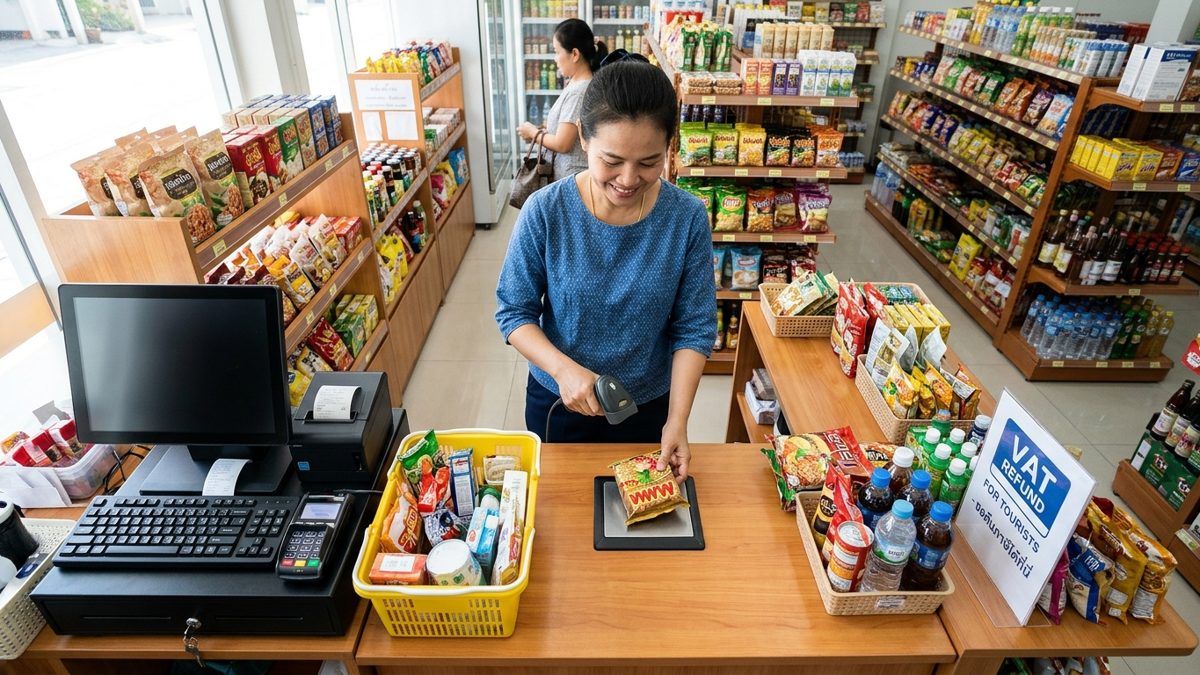
A VAT refund is the right to claim a refund of Value Added Tax (VAT) granted by the Thai government to foreign tourists who purchase goods from authorized participating stores and take those goods out of Thailand within 60 days from the purchase date, based on the Destination Principle under Section 84/4 of the Revenue Code [1][4]. For prominent tourism hubs such as Chiang Mai, obtaining approval to display the "VAT REFUND FOR TOURISTS" logo significantly enhances business credibility and provides a strong incentive for foreign travelers to make purchases.
However, the legal responsibilities of a VRT store are strictly defined. Business owners frequently hold two major misconceptions. First, they assume sales to foreign tourists are exempt from tax like export sales under Section 80/1 [4]. Second, they assume the merchant must pay cash out of pocket at the checkout counter to refund the VAT to the customer. Operational errors—such as failing to prepare the Kor.Thor.9 report within 3 days or deducting the VAT on Form P.P.10 from the output VAT on Form P.P.30—will result in retroactive tax assessments, penalties of 1 to 2 times, and a surcharge of 1.5% per month under the Revenue Code [2][4], as well as potential immediate revocation of VRT store status.
Review of Legal Principles and Regulations Concerning VAT Refunds for Tourists
The VAT Refund for Tourists scheme is governed by the Revenue Code and several notifications issued by the Ministry of Finance and the Revenue Department, establishing the following compliance framework for retailers [1][4]:
- Section 84/4 of the Revenue Code: Empowers the Director-General of the Revenue Department to prescribe rules, procedures, and conditions for refunding VAT to tourists taking goods out of the Kingdom [1][4].
- Notifications of the Director-General of the Revenue Department on VAT (No. 90) and (No. 116): Prescribe qualifications of eligible juristic entities, issuance criteria for refund claim forms (Form P.P.10), and eligibility requirements for foreign tourists [1].
- Notification of the Director-General of the Revenue Department on VAT (No. 232): Establishes rules, procedures, and conditions for preparing tourist VAT refund claim forms electronically (e-P.P.10 system) as an alternative to paper forms [3].
- Section 82/3 of the Revenue Code: Mandates that registered persons calculate and remit VAT for each tax month by deducting input tax from output tax. VRT stores must include all sales and output VAT from tourist transactions in their monthly P.P.30 return under this section in every respect [2][4].
- Sections 86/4 and 86/6 of the Revenue Code: Section 86/4 governs full tax invoice requirements, while Section 86/6 governs abbreviated tax invoices for retailers. Under the VRT system, stores must issue full tax invoices specifying the tourist's full name, overseas address, and passport number pursuant to the Director-General's notifications [1][4].
- Section 90/4(6) of the Revenue Code: Imposes criminal penalties for VAT-related fraud. Issuing tax invoices or P.P.10 claim documents without actual sales, or conspiring to claim unlawful refunds, carries imprisonment from 3 months to 7 years and fines from 2,000 baht to 200,000 baht [4].
Qualifications and Required Documents Before Applying to Become a VRT Store
Applying to become an authorized VRT store requires meeting specific criteria set by the Revenue Department. A juristic person (company) must verify its corporate structure and prepare all required documentation prior to filing [1].
1. Business Operator Qualifications
- Organizational Form: Must be a juristic entity established under Thai law, specifically a limited company (Co., Ltd.), public limited company, or registered partnership (ordinary individuals, non-juristic bodies of persons, or unregistered joint ventures cannot apply) [1].
- VAT Registration Status: Must be an active VAT-registered business holding a valid P.P.20 certificate [1].
- Paid-up Registered Capital Criteria:
- Premises located in Bangkok: Paid-up registered capital of not less than 2,000,000 baht [1].
- Premises located in provincial regions (including Chiang Mai): Paid-up registered capital of not less than 500,000 baht [1].
- Nature of Establishment: Must have a permanent commercial premises, a fully operational storefront for selling goods, and store signage matching its commercial registration [1].
- Tax Compliance History: Must have no outstanding tax arrears and maintain a solid record of tax compliance with the Revenue Department [1].
2. Supporting Documents Required for the Application
All supporting copies must be certified as true copies by authorized company directors with the corporate seal affixed (if applicable) [1]:
- Application Form Kor.Thor.1: Application form for approval as an authorized goods vendor for tourists, submitted in 3 sets [1].
- Form Kor.Thor.1.1: Branch details form, submitted in 3 sets (only if applying for more than one branch location) [1].
- Company Affidavit: Company affidavit (DBD company certificate) issued by the Department of Business Development (DBD) within the last 6 months, including registered company objectives [1].
- VAT Registration Certificate (P.P.20): Copies of the VAT certificate for the head office and every branch applying for authorization [1].
- Property Ownership Proof or Lease Agreement: Lease agreement, service agreement, or consent letter to use premises, accompanied by a copy of the house registration for the location [1].
- Location Map and Premises Photos: A clear sketch map, exterior photographs showing store signage, checkout counters, and product display areas [1].
- ID Card and House Registration Copies: For authorized directors signing on behalf of the company [1].
- Power of Attorney: If authorizing an agent, stamped with 10 baht duty stamp (for a single act) or 30 baht (for multiple acts), accompanied by a copy of the attorney-in-fact's ID card [1][4].
Application Procedures and Troubleshooting Common Hurdles
The procedure for how to get approved as a vat refund store involves sequential steps and coordination with revenue officers as follows [1]:
1. Step-by-Step Application Process
- Prepare Documents and Fill Out Form Kor.Thor.1 / Kor.Thor.1.1: Ensure the corporate name, 13-digit tax ID, and address match the P.P.20 registry exactly [1].
- Submit to Revenue Authorities:
- Premises in Bangkok: Submit to the VAT Refund for Tourists Management Bureau at the Revenue Department headquarters, or the Area Revenue Office having jurisdiction [1].
- Premises in the provinces (e.g., Chiang Mai): Submit to the Area Revenue Office or Area Revenue Branch Office having jurisdiction over the establishment [1].
- On-Site Premises Inspection: Area revenue officials will schedule an on-site visit to inspect store readiness, physical inventory presence, and commercial invoicing systems [1].
- Notification of Result and Approval Letter: Processing standard takes approximately 30 working days. Upon approval, the store receives an "Approval Notification Letter (Form Kor.Thor.2)" along with an authorized VRT merchant code [1].
- Requesting P.P.10 Booklets or Activating e-P.P.10: Once approved, the store submits Form Kor.Thor.7 to request physical P.P.10 claim booklets (along with official stamps and decals) or applies for electronic e-P.P.10 integration via the Revenue Department web service [1][3].
2. Common Application Issues and Solutions (Troubleshooting)
- Paid-up Capital Below Requirement: Even if registered capital states 500,000 baht or 2,000,000 baht, if financial statements indicate shares are only partially paid up (e.g., 25%), the application will be denied. Solution: Hold a shareholders' meeting to call up remaining share capital in full and document clear payment records in the accounts before applying [1].
- Address Discrepancies with P.P.20: Unit numbers, floors, or branch premises were modified without notifying the VAT registry. Solution: File Form P.P.09 to update VAT registration records to reflect reality at least 15 days prior to submitting Form Kor.Thor.1 [4].
- Ineligible Goods or Mixed Premises: A shop registered for handicraft sales operates a café or massage service on the same floor without spatial separation. Solution: Clearly demarcate physical sales areas for take-away retail goods from service areas.
To understand overall VAT management and strengthen your financial backend, read our guide on Check Now! Essential Facts Before Claiming a VAT Refund Without Losing Tax Benefits.
Post-Approval Tax and Document Duties: Kor.Thor.9 Form and the Difference Between VRT and P.P.30
Becoming an authorized VRT merchant entails additional statutory compliance obligations that accounting and finance staff must monitor closely to prevent penalties and tax liabilities [2][4].
1. Invoicing and Documentation Duties upon a Sale
When an eligible tourist requests a VAT refund document, the store must verify and follow these steps [1]:
- Verify Tourist Eligibility: Must be a non-Thai national, non-resident, staying in Thailand for no more than 180 days in that calendar year, and not an airline crew member on duty [1].
- Purchase Threshold: Total purchase amount must be not less than 2,000 baht (including 7% VAT) at the same store on the same day [1].
- Issue a Full Tax Invoice: Issue a full tax invoice under Section 86/4 of the Revenue Code, stating the tourist's full name, foreign address, and Passport Number accurately [1][4].
- Issue Form P.P.10: Accurately record the goods description and 7% VAT. Attach the original tax invoice to Form P.P.10 and hand it to the tourist in an official VRT envelope for airport customs and tax inspection [1].
2. Duty to Prepare the Kor.Thor.9 Report Within 3 Days
Under Director-General notifications, the retailer must complete the "Report on the Issuance of VAT Refund for Tourists Applications (Form Kor.Thor.9)" within 3 days from the date of issuing Form P.P.10 to the tourist [2]. The report must detail booklet/running numbers of Form P.P.10, tax invoice numbers, sale dates, customer name, nationality, passport number, goods value, and VAT amount. The store must retain Form Kor.Thor.9 along with copies of Form P.P.10 and copies of tax invoices at the premises for at least 2 years for tax audits [2].
3. Filing P.P.30: Critical Caution for VRT Stores
The core accounting rule is that sales under the VRT scheme are normal taxable sales subject to standard 7% VAT in full [2][4]. The merchant must collect the retail price inclusive of 7% VAT from the tourist at point of sale, include these sales and output VAT in the monthly P.P.30 (monthly VAT return), and remit the tax by the 15th of the following month (or the 23rd via e-Filing) [2][4].
Strict Requirement: Never deduct the VAT amount shown on Form P.P.10 from output VAT in Form P.P.30, nor record it as tax-exempt revenue. The Revenue Department refunds the tourist directly from public state funds at international airports. If a store improperly deducts this tax, it constitutes an under-reporting of output VAT, triggering severe statutory penalties and surcharges [2][4]. For monthly return deadlines and procedures, review our guide on P.P.30 Filing Guide for Beginners: Step-by-Step Instructions to Avoid Mistakes and Penalties.
Eligible Goods, Prohibited Items, and Inspection Criteria for Luxury Goods
Not all retail items are eligible for Form P.P.10. Merchants must strictly classify items according to Revenue Department regulations [1]:
| Product Category | Example Items | Form P.P.10 Eligibility |
|---|---|---|
| Eligible Goods | Apparel, Thai silk, handicrafts, finished silverware, souvenirs, packaged snacks, electronics | Eligible (minimum 2,000 baht/day at the same store) [1] |
| Statutory VAT-Exempt Goods | Fresh agricultural produce, fresh flowers, fresh fruits, textbooks, books, magazines | Ineligible, as these items carry no 7% VAT base from the start [4] |
| All Types of Services | Hotel lodging, massage and spa treatments, restaurant dining, car rentals, admission tickets | Ineligible, as services are consumed domestically within Thailand [1] |
| Prohibited Export Items | Weapons, explosives, antiques or artifacts without a Fine Arts Department permit, narcotics | Strictly prohibited from the scheme [1] |
| Unset Precious Gemstones | Unset diamonds, loose gemstones, gold bars/bullion | Ineligible for tourist refund [1] |
Inspection Criteria for High-Value Goods (Luxury Goods)
Under updated Revenue Department regulations (effective since 1 December 2023 through 2026), specific value thresholds trigger mandatory secondary physical inspection at customs and revenue checkpoints at international airports [1]:
- 9 Categories of Specific Goods Valued at 40,000 Baht or More per Item: Jewelry set in ornaments, gold ornaments, watches, eyeglasses, pens, smartphones, laptops/tablets, handbags, and belts [1].
- Hand-Carried Items Valued at 100,000 Baht or More per Item: Any category of goods carried onto the aircraft as cabin luggage [1].
Merchant Duty: Store staff must actively remind tourists that these high-value items cannot be packed inside checked baggage. The tourist must carry them as hand luggage and present them to revenue officials at the airport refund counter past immigration, or the refund will be denied [1].
Comparison: Paper-Based P.P.10 Booklet vs. Electronic e-P.P.10 System
The Revenue Department provides the official e-VAT Refund for Tourists system. Stores can evaluate which method aligns best with their operations [3]:
| Comparison Point | Traditional Paper Booklets (P.P.10) | Electronic System (e-P.P.10) |
|---|---|---|
| Format | 4-ply carbonized paper forms; requires Form Kor.Thor.7 to replenish booklets [1] | Digital data transmitted via web application or direct API to Revenue Department servers [3] |
| Issuance Workflow | Handwritten or typed, taking 5–10 minutes per transaction with high error risk | Passport scanner auto-populates traveler data, completing forms in 1–2 minutes [3] |
| Kor.Thor.9 Reporting | Merchant must manually enter data into Kor.Thor.9 logbooks within 3 days [2] | System automatically generates Kor.Thor.9 reports on cloud storage [3] |
| Document Storage | Physical copies must be stored securely on premises for at least 2 years [2] | Stored on secure electronic servers, reducing physical space and loss risks [3] |
| Tourist Experience | Must carry original physical paperwork to customs and airport refund counters [1] | Track status via the Thailand VRT mobile app and scan barcodes for quick payouts [3] |
Case Study: Tax Calculation and Accounting Entry for a Chiang Mai Craft Store (Hypothetical Example)
To demonstrate correct VAT calculations and bookkeeping entries, consider this hypothetical example of "Chiang Mai Celadon Craft Co., Ltd.," an authorized VRT merchant registered for VAT in Mueang Chiang Mai District [1].
1. Business Transaction
On 10 November 2026, a Spanish tourist purchased celadon ceramics and handwoven textiles totaling 10,700 baht (price inclusive of 7% VAT). The customer presented an original foreign passport requesting a P.P.10 form.
2. Tax Calculation
- Gross Sales (VAT Inclusive): 10,700.00 baht (meets the minimum 2,000 baht threshold) [1].
- Taxable Base (Pre-VAT Amount): 10,700 × (100 ÷ 107) = 10,000.00 baht [4].
- 7% VAT: 10,700 - 10,000 = 700.00 baht [4].
3. Store Accounting Entry (as of 10 November 2026)
| Account Description | Debit (Baht) | Credit (Baht) |
|---|---|---|
| Debit: Cash / Bank Deposits | 10,700.00 | - |
| Credit: Sales Revenue | - | 10,000.00 |
| Credit: Output VAT (VRT) | - | 700.00 |
4. Compliance Workflow of the Store
- Check passport details to verify the tourist has stayed in Thailand under 180 days [1].
- Issue a full tax invoice indicating name, overseas address, and passport number, together with Form P.P.10 showing 700.00 baht VAT [1].
- Record the sale in the Kor.Thor.9 report by 13 November 2026 (within 3 days from the P.P.10 date) [2].
- Monthly P.P.30 Filing for November 2026 (by 15 December 2026): Include 10,000 baht in total sales and 700 baht in output VAT in the November return, remitting the full balance. Do not deduct the 700 baht [2][4].
- The tourist presents the goods and Form P.P.10 at Chiang Mai International Airport (CNX). The Revenue Department processes and refunds the 700 baht (less processing fees) directly to the traveler [1].
Best Practices and Support from the Chiang Mai Accounting Team
Becoming a VRT store expands access to foreign tourist retail markets, but documentation accuracy and post-sale tax discipline are vital to mitigate audits. For businesses across Chiang Mai and Northern Thailand, aligning local systems with Area Revenue Office standards is essential.
If your business faces challenges managing Kor.Thor.9 logs, reconciling output VAT on Form P.P.30, or transitioning from paper forms to digital e-P.P.10, YMTD Accounting Partner, providing professional accounting services in Chiang Mai, suggests three practical measures:
Key Implementation Steps:- Upgrade POS Systems for Passport Data: Configure Point-of-Sale or ERP invoicing software to capture passport numbers and print full tax invoices meeting Section 86/4 standards promptly upon request [1][4].
- Implement Daily Kor.Thor.9 Closing Procedures: Rather than waiting for the 3-day statutory deadline, complete Kor.Thor.9 reporting on a daily closing schedule to prevent missing copies [2].
- Review Financial Statements and Paid-up Capital Before Filing Kor.Thor.1: Consult an auditor (CPA) or accountant to ensure paid-up registered capital in financial statements meets the 500,000 baht provincial minimum [1]. You can engage our comprehensive accounting services to review records, fixed asset registers, and financial reports prior to revenue inspections.
Frequently Asked Questions
What is the minimum purchase amount for tourists to request a P.P.10 form, and can receipts from different days be combined?
The minimum purchase amount must be at least 2,000 baht (including 7% VAT) at the same store on the same calendar day. Invoices from different days cannot be aggregated, even from the same store or branch [1].
How do P.P.10 and P.P.30 differ, and must the store refund the VAT amount to tourists directly?
Form P.P.10 is the tourist refund claim application issued by the store for the traveler to present at airport tax desks. Form P.P.30 is the merchant's monthly VAT return filed with the Revenue Department. The store does not refund cash directly to the customer; it collects full VAT and remits 7% output tax via Form P.P.30 as normal [1][2][4].
After being approved as a VRT store, what reporting duties does the business have (what is Kor.Thor.9)?
The merchant must prepare the "Report on the Issuance of VAT Refund for Tourists Applications (Form Kor.Thor.9)" within 3 days from the date of issuing Form P.P.10, and must maintain this report together with copies of tax invoices at the premises for at least 2 years [2].
What types of goods are not eligible for a P.P.10 form for a VAT refund for tourists?
Ineligible items include all services (hotel accommodation, spa, restaurant meals), statutory VAT-exempt goods (fresh agricultural produce, books), loose/unset gemstones, gold bullion, and prohibited export goods like unlicensed antiques or weapons [1][4].
Conclusion
Following the correct process on how to get approved as a vat refund store provides a compelling commercial edge for Thai retailers and artisans catering to foreign visitors. However, companies must maintain strict accounting controls: checking the 2,000 baht single-day purchase threshold [1], completing Kor.Thor.9 reports within 3 days [2], and reporting all output VAT in full on Form P.P.30 without deducting tourist refunds [2][4]. Establishing compliant backend accounting procedures from the outset protects business owners from retroactive tax assessments and penalties over the long term.
References
- The Revenue Department. (2023). Conditions and Criteria for VAT Refund for Tourists. Retrieved from https://vrtweb.rd.go.th/38.html
- VAT Refund for Tourists Management Bureau, The Revenue Department. (2023). Frequently Asked Questions and Guidelines for Participating Retailers (FAQ). Retrieved from https://vrtweb.rd.go.th/69.html
- The Revenue Department. (2023). Procedures for VAT Refund for Tourists via Electronic System (e-P.P.10 Process). Retrieved from https://vrtweb.rd.go.th/106.html
- Office of the Council of State. (2026). Revenue Code Governing Value Added Tax (Chapter 4). Retrieved from https://ratchakitcha.soc.go.th/
Need to organize your VRT tax accounting or prepare application documents professionally?
Contact YMTD Accounting Partner Chiang Mai for an evaluation and accounting setup tailored to your enterprise.
Call 081-542-3019 | LINE: @premwittawat
Note: This article provides general educational information based on laws and regulations effective as of 7 November 2026, which may change. As business circumstances vary, consult a professional advisor prior to making operational decisions.